QIT (Quantitative, Investment, Trends) UI
Access the UI here (note: currently only for personal use)
General Features
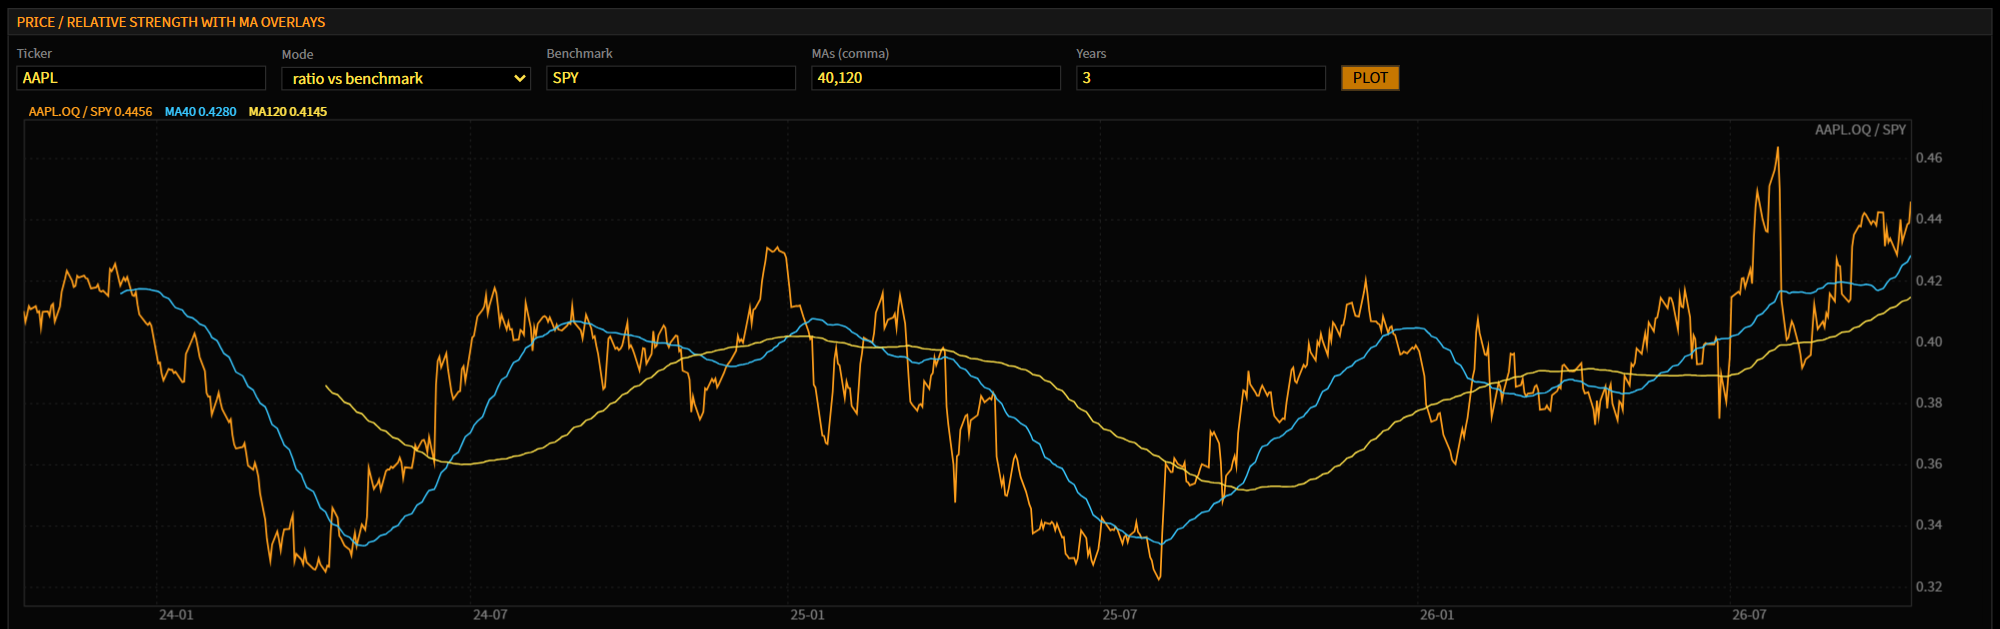
Ability to update data using (currently) LSEG info through both scheduled pulls and manuals, originally used yfinance. PostgreSQL queries to pull data, alongside a charts of any asset in database, detailing relevant moving averages and ratios. Paper trading system, can trade in real-time directly according to the pair of equities strategies or manually with both equities and options.
Volatility and Options
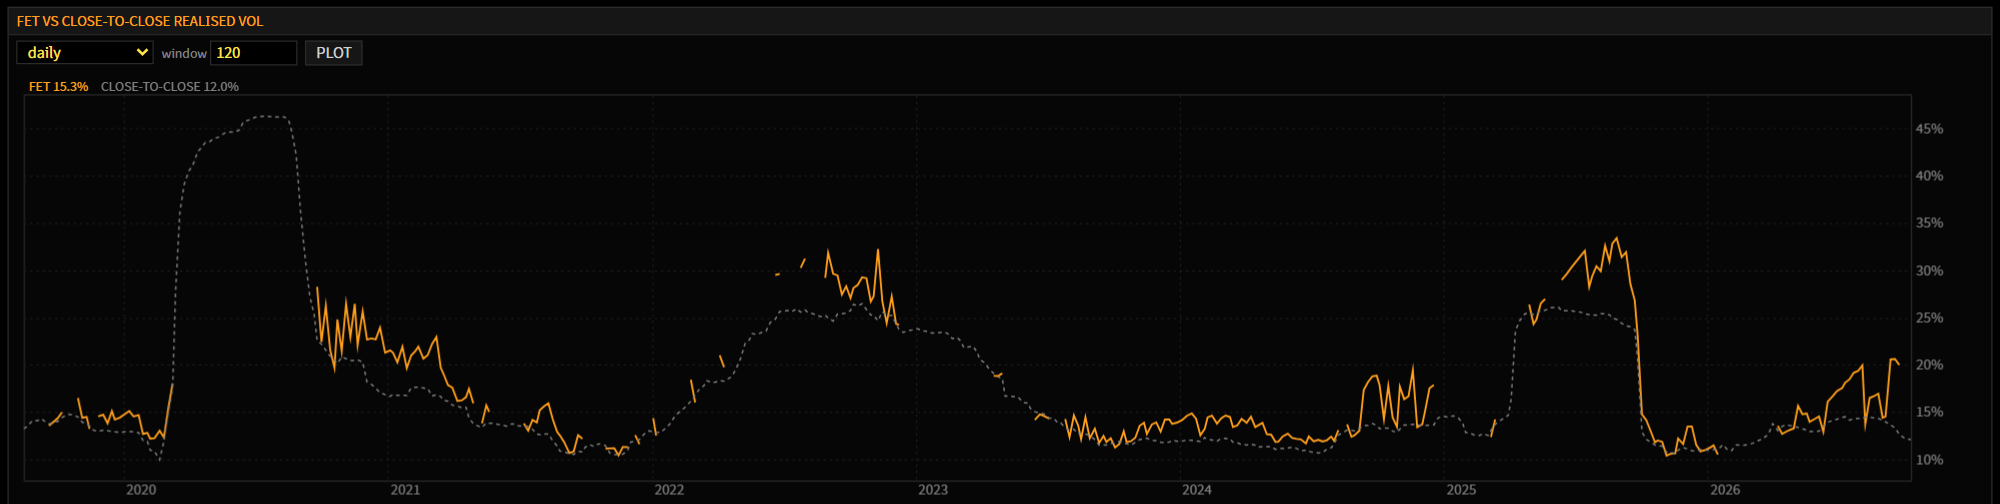
Currently limited true historical options data as LSEG Tick History access is WIP. 2021 full-chain on SPY, otherwise some options data on AAPL. IV is estimated using methods described in Euan Sinclair's Volatility Trading, with Black-Scholes to provide out-of-database historicals and Greeks.
Backtester and Optimizer
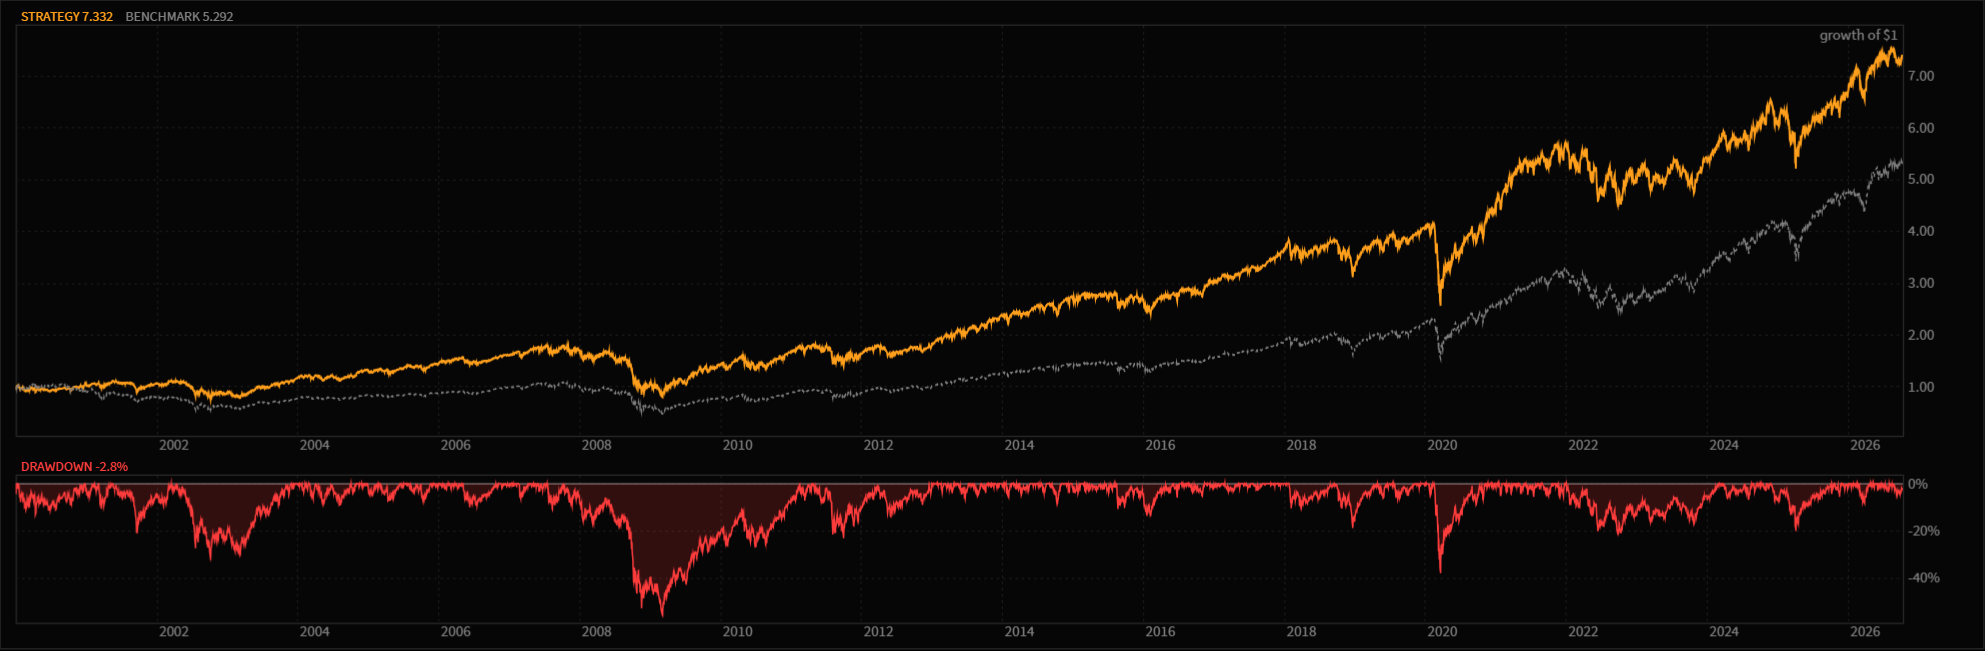
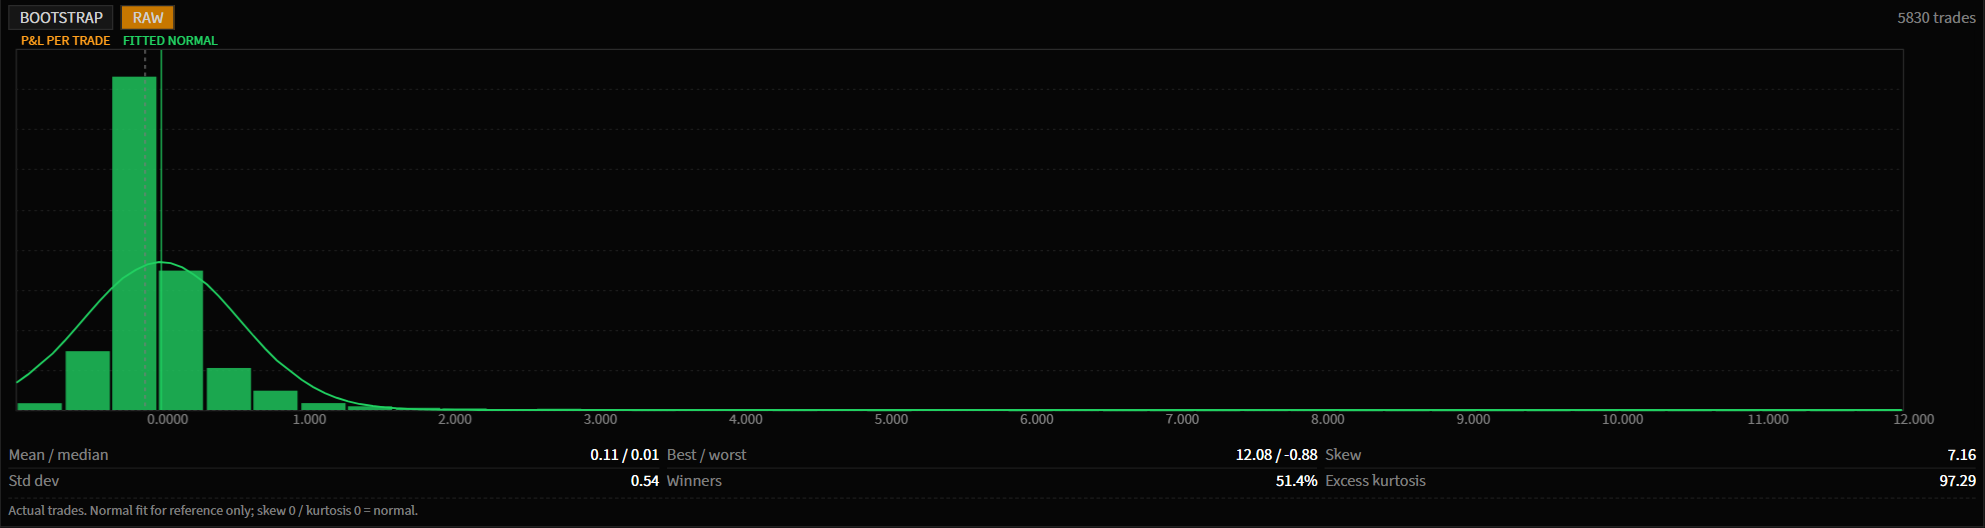
A long-term backtester able to run tests starting from ~1990 to present on equities, roughly 2016 to present on options. Can deploy one of three personal equity strategies (written as Python files), or pick from a variety of classical options strategies, such as the ones outlined in Hull's Options, Futures, and Other Derivatives chatper 12. For both equities and options, implements bet sizing with Sinclair Ch.8, optimal asset selection scored as percentiles or vs. benchmark. Provides a variety of parameters to work with and and change manually, along with .csv files of the full backtest trade history, and charts detailing industry allocations, overall returns, normally-distributed returns, and a table of various portfolio metrics.